Get a Land Insurance quote from our New Jersey specialists
Innovate Insurance Agency
What is Land Insurance & Who May Need It?
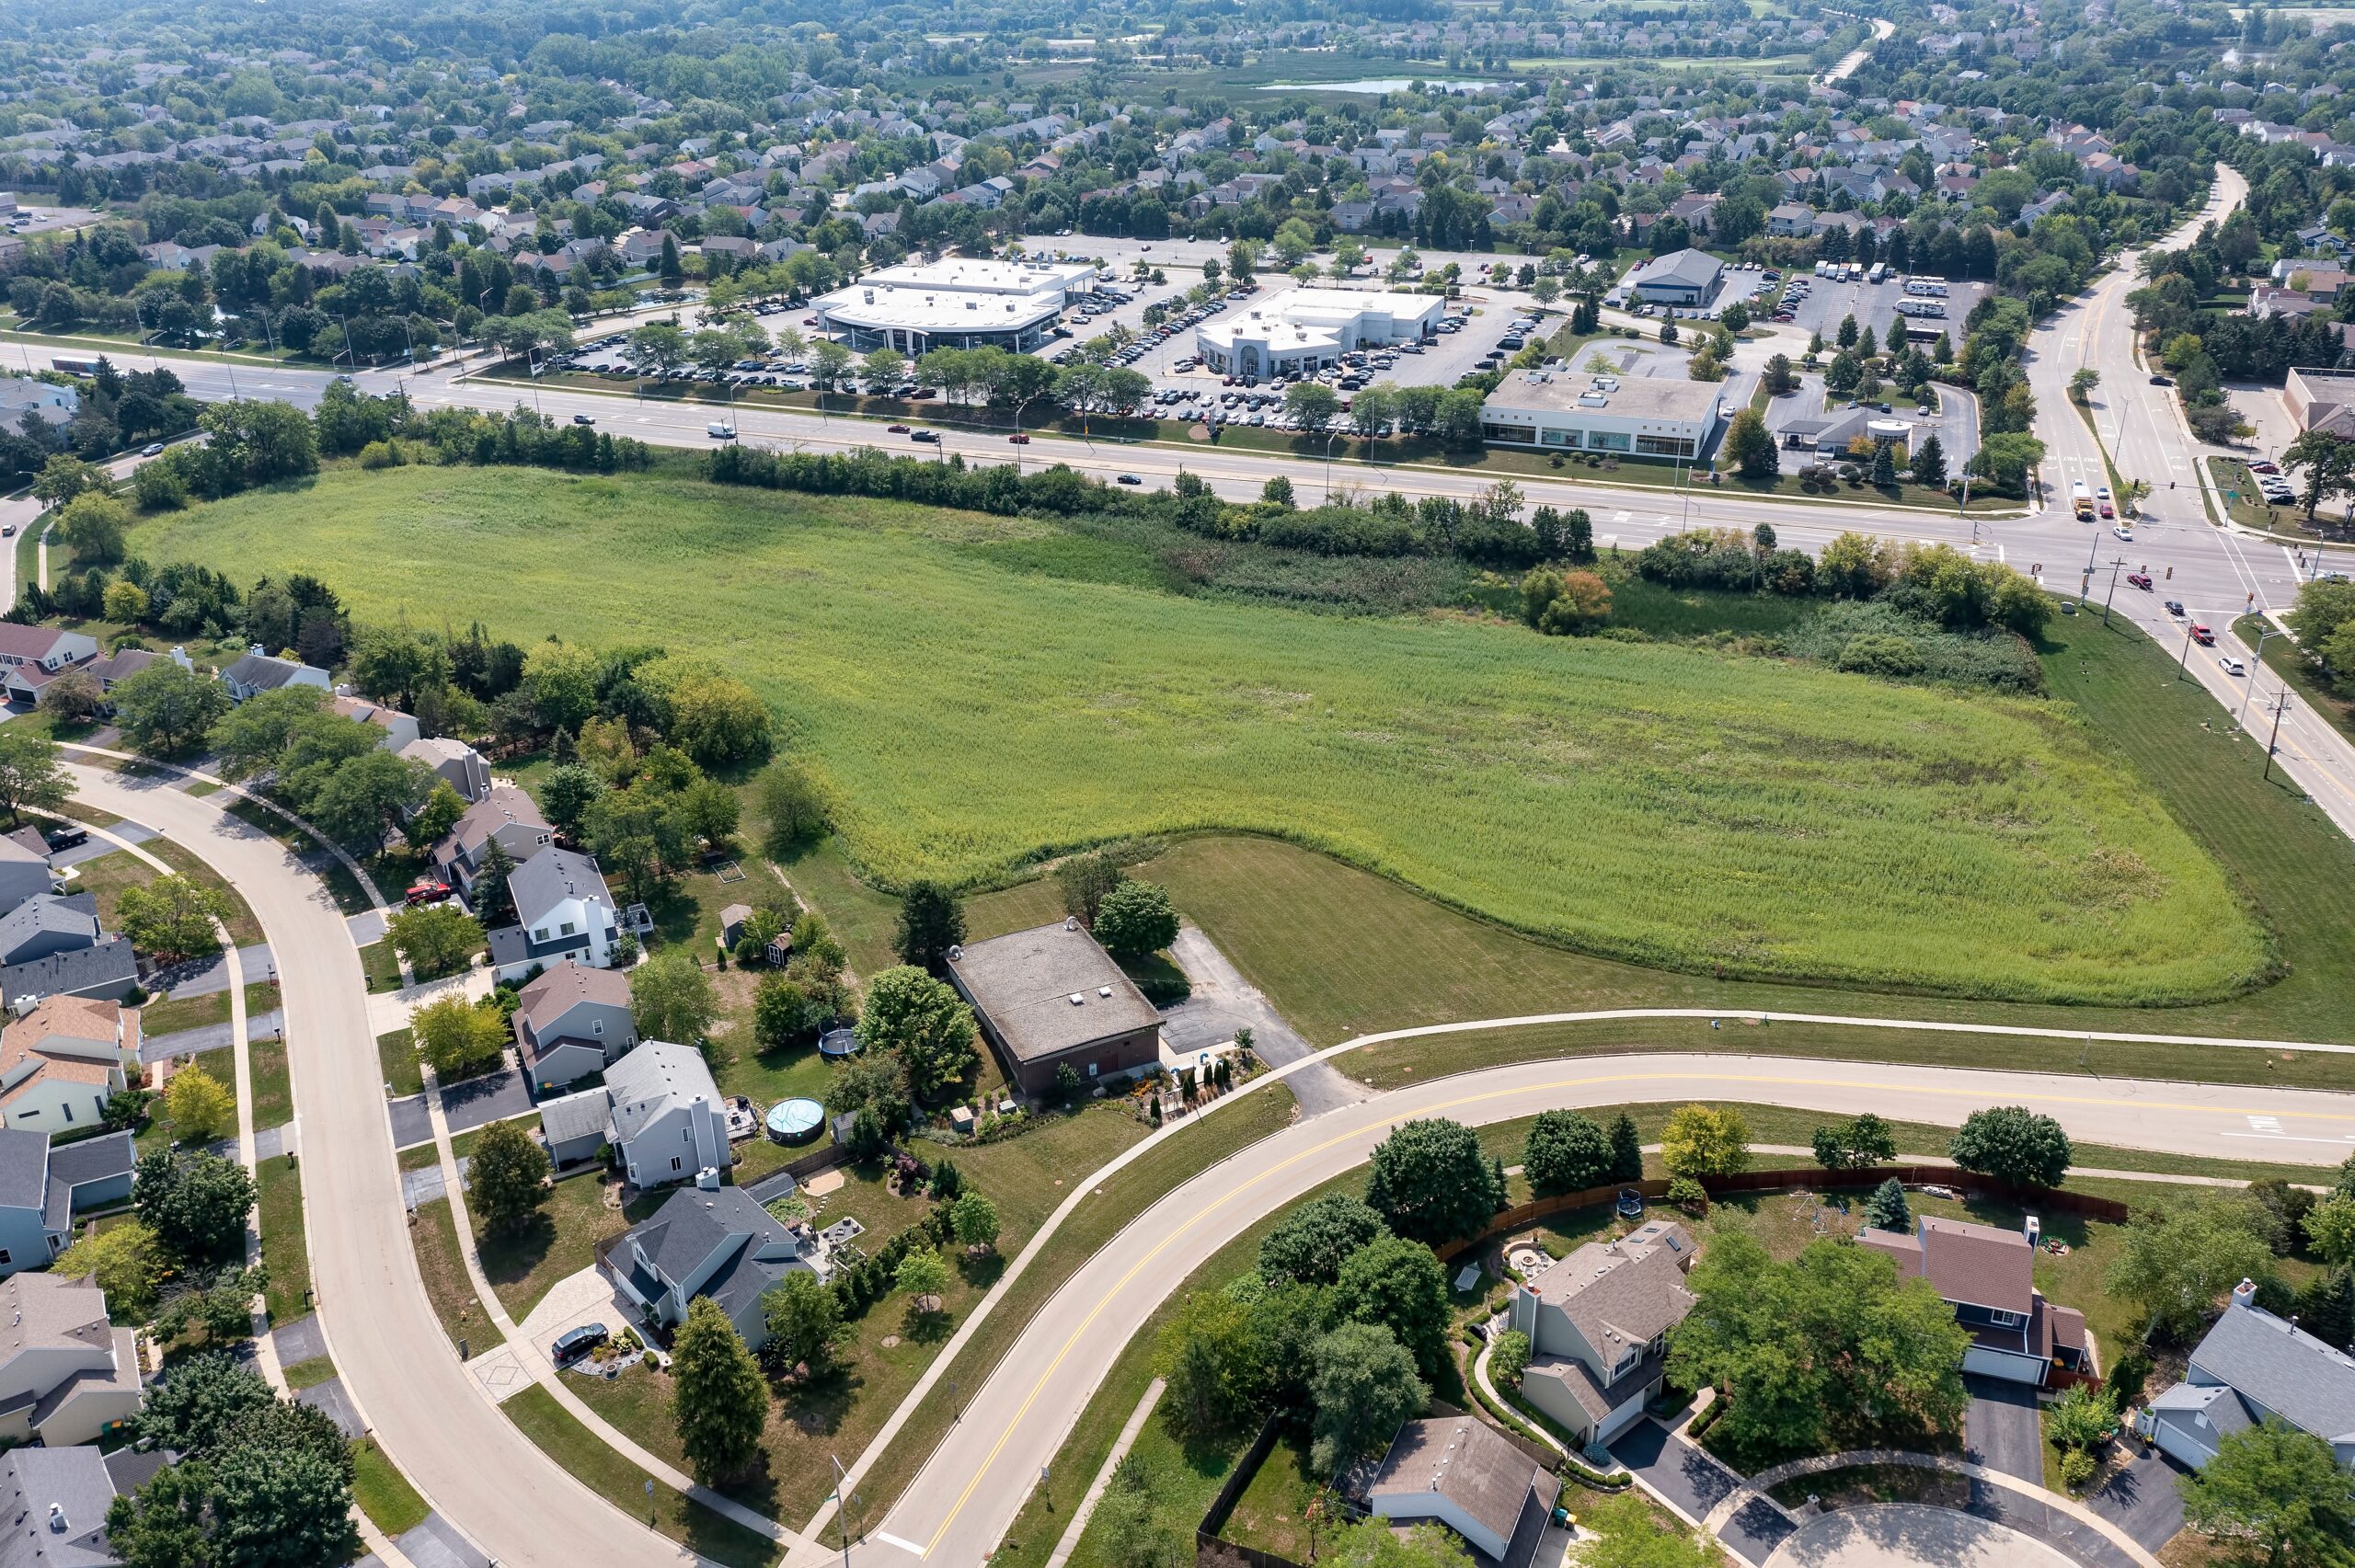
Land Insurance is a specialized type of premises liability coverage designed specifically to protect property owners from severe financial loss if an accident or injury occurs on their undeveloped acreage. Many landowners in New Jersey mistakenly believe that because their land is completely vacant, devoid of any homes, buildings, or commercial structures, they carry absolutely zero risk of being sued.
Unfortunately, this is a dangerous misconception that can lead to financial ruin. In reality, as a property owner, you are legally responsible for maintaining a safe environment on your land, even if you do not actively use it or live on it. Whether you own a quiet wooded lot in Sussex County, a scenic coastal parcel near Cape May, or a suburban plot awaiting future development in Middlesex County, securing vacant land insurance is an essential step in protecting your personal or business assets. This type of policy primarily focuses on premises liability protection. This means that if a trespasser, a neighbor, a hunter, or an invited guest wanders onto your property and suffers an injury, your policy will step in to cover their medical bills, your legal defense fees, and any court-ordered settlements or judgments up to your policy limits.
Without this protection, a single lawsuit resulting from an ATV accident, a slip-and-fall on uneven terrain, or a drowning in a natural pond on your property could jeopardize your entire financial future. State courts hold landowners to strict standards of care regarding known hazards, making this coverage a vital safety net for any individual or corporate entity holding raw acreage.
What is a Real-World Example of Land Insurance in Action?
To understand the practical importance of this coverage, let us look at a real-world example of this coverage in action within New Jersey. Imagine a private citizen who owns twenty acres of undeveloped woodland in Warren County. Although the owner has clearly posted signs around the perimeter, local residents frequently use an old trail on the property for hiking and walking their dogs. During an autumn afternoon, a hiker trips over a partially buried metal pipe left behind by a previous owner, sustaining a severe compound fracture that requires multiple surgeries and months of physical therapy. The injured hiker files a major premises liability lawsuit against the landowner to cover medical expenses, lost wages, and pain and suffering.
Without coverage, the landowner would be forced to pay thousands of dollars out of pocket simply to hire a defense attorney to represent them in court, let alone pay for the actual settlement. Fortunately, because the landowner had a dedicated policy in place, their insurance provider immediately stepped in to handle the legal defense, hire local counsel, and ultimately settle the claim out of court. This real-world scenario highlights how easily an uninvited guest can create a massive financial liability for an unsuspecting landowner.
To illustrate the scale of this risk, the table below provides a detailed snapshot of land ownership risks, active policies, and claims activity across the state for the current year.
| Metric for Current Year | State Statistics | Key Takeaway for Landowners |
|---|---|---|
| Active Land Policies | 14,250 | Growing adoption among private acreage owners |
| Average Annual Liability Claims Filed | 1,120 | Trespassing and recreational accidents represent major risks |
| Average Claim Settlement Amount | $42,500 | Defending a lawsuit without insurance is financially devastating |
| Primary Policy Holders | Private Owners (65%) | Individual families hold the majority of vacant land policies |
How Much Does Land Insurance Cost?
The cost of securing this coverage in New Jersey is remarkably affordable, particularly when you contrast the annual premium against the catastrophic costs of an uninsured liability lawsuit. Insurance companies calculate premiums based on several key risk factors, including the total acreage of the property, its geographical location, its proximity to public roads, and how the land is utilized. For example, a flat, cleared vacant lot in a quiet suburban neighborhood will generally cost significantly less to insure than a large, heavily wooded parcel featuring water hazards, steep cliffs, or active hunting leases.
To help you understand the typical costs associated with this coverage, we have compiled a pricing table outlining the estimated annual premiums for vacant land insurance across various common property profiles in the state.
| Property Type & Size | Coverage Limit (Occurrence/Aggregate) | Estimated Annual Premium |
|---|---|---|
| Suburban Lot (Under 1 Acre) | $1,000,000 / $2,000,000 | $150 – $250 |
| Rural Wooded Acreage (1 to 10 Acres) | $1,000,000 / $2,000,000 | $250 – $400 |
| Large Acreage / Hunting Land (10 to 50 Acres) | $1,000,000 / $2,000,000 | $400 – $650 |
| Waterfront Property (Under 5 Acres) | $1,000,000 / $2,000,000 | $350 – $550 |
What Should You Consider and What Are the Limitations of Land Insurance?
When you are searching for the right Land Insurance policy, it is crucial to understand both the scope of your coverage and any inherent limitations that come with these policies. The primary objective of vacant land insurance is to provide robust premises liability protection; however, it does not cover physical damage to the land itself. For instance, if a severe storm causes soil erosion, a sinkhole develops, or a wildfire destroys thousands of dollars worth of mature timber on your property, a standard liability policy will not provide any financial compensation for those losses.
Additionally, standard policies come with strict usage limitations. If you decide to break ground and begin constructing a home, a barn, or a commercial building on the property, your vacant land coverage will immediately become invalid. At that point, you must transition the policy to a course of construction or builder’s risk policy to ensure continuous coverage. Furthermore, any pre-existing structures on the land, such as an abandoned farmhouse, an old storage shed, a silo, or a boat dock, are typically excluded from coverage unless they are explicitly declared and added to the policy via an endorsement.
If you plan to lease your land to others for agricultural use, recreational hunting, or timber harvesting, you must notify your agent, as these commercial activities require specialized commercial endorsements to remain fully protected.
What Other Coverages Work Best with Land Insurance?
While Land Insurance offers foundational protection for undeveloped property, it is rarely the only insurance policy that landowners should consider. Depending on how you hold title to the land and your future plans for the property, combining your policy with other specialized coverages can help you build a seamless shield against financial loss.
For example, if your land is held under a business entity or a limited liability company (LLC), integrating your policy with a commercial general liability framework or a commercial umbrella policy is highly recommended to protect your broader corporate assets.
To help you navigate these options, the comparison table below outlines the other common insurance coverages that property owners typically utilize in conjunction with their primary land policy.
| Related Coverage | Primary Purpose | How It Works with Land Insurance |
|---|---|---|
| Umbrella Insurance | Extends liability limits beyond standard policy caps | Provides extra protection if a major injury claim exceeds your $1M limit |
| Builder’s Risk Insurance | Covers structures under construction | Replaces vacant land coverage once you break ground on a new building |
| Inland Marine Insurance | Covers mobile equipment and tools | Insures tractors, ATVs, or chainsaws used to maintain the property |
| Hunting Lease Liability | Covers liability specific to hunting activities | Protects you if you lease your acreage to recreational hunters |
What Are the Key Statistics for Land Insurance?
Examining the local statistics surrounding land ownership highlights why this coverage is such a vital asset for property owners. Our state is well-known as the most densely populated in the nation, which directly translates to a much higher probability of human interaction on private land. With an extensive network of state parks, hiking trails, and outdoor recreational areas bordering private properties, landowners face a constant influx of liability exposure from hikers, hunters, and off-road vehicle riders.
According to regional legal databases, premises liability claims represent one of the most common categories of civil lawsuits filed in the state each year. Property owners who fail to secure their boundaries or neglect known hazards on their acreage are especially vulnerable to legal action. Statistically, over sixty percent of vacant land liability claims in the region involve unauthorized recreational activities, such as riding dirt bikes or ATVs on private trails.
Given that the average cost of defending a liability lawsuit in court can easily exceed tens of thousands of dollars in legal fees alone, having a dedicated insurance policy is the most effective way to safeguard your hard-earned assets from unexpected claims.
Who is Land Insurance Designed for and How Can We Help?
This specialized coverage is specifically designed for individual landowners, real estate investors, builders, developers, and families who own undeveloped acreage throughout the state. Whether you have inherited a historic family plot, purchased a beautiful parcel of land for a future retirement home, or hold acreage as a long-term investment, protecting that asset from unforeseen liability claims is our top priority.
We proudly help over 78 active customers with Land Insurance in New Jersey, providing tailored insurance solutions that match the unique characteristics of each property. We understand that no two pieces of land are identical, which is why we take a personalized approach to help you identify potential risks and secure the exact coverage you need.
We invite you to contact our office today to receive a free, customized quote without any sort of obligation. Let our experienced team do the heavy lifting so you can enjoy the peace of mind that comes with knowing your investment is secure.
Get a Quote
Share your details with us, and our team of friendly agents will be in touch with you soon!